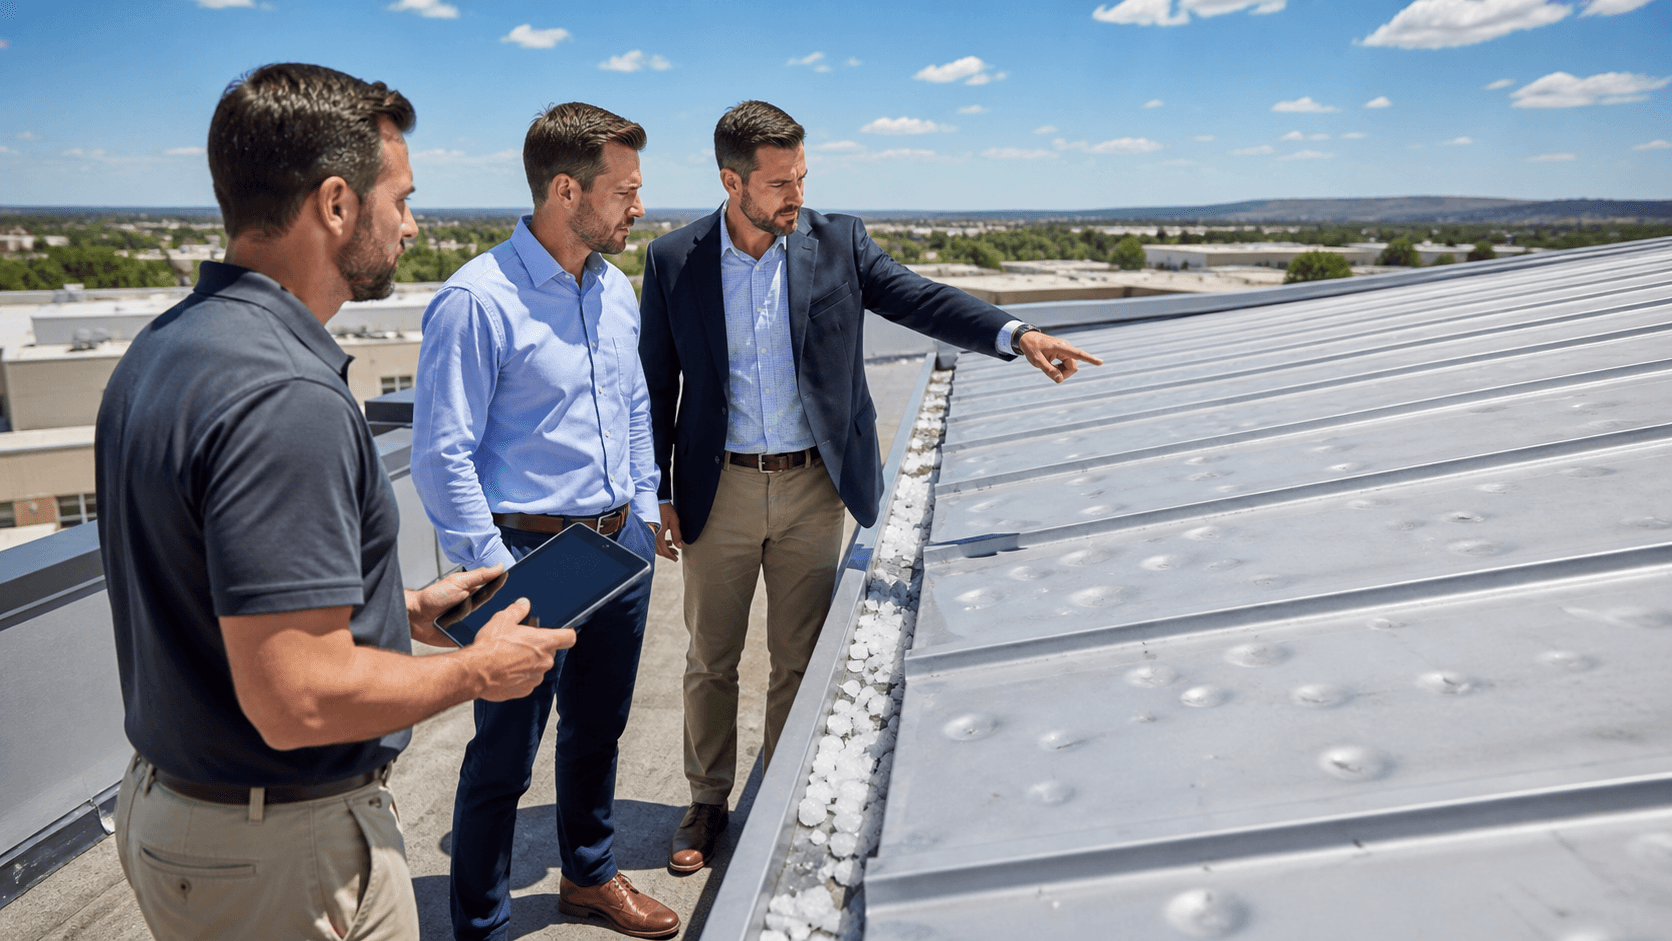
Hidden Exposure in Texas Hail Claims
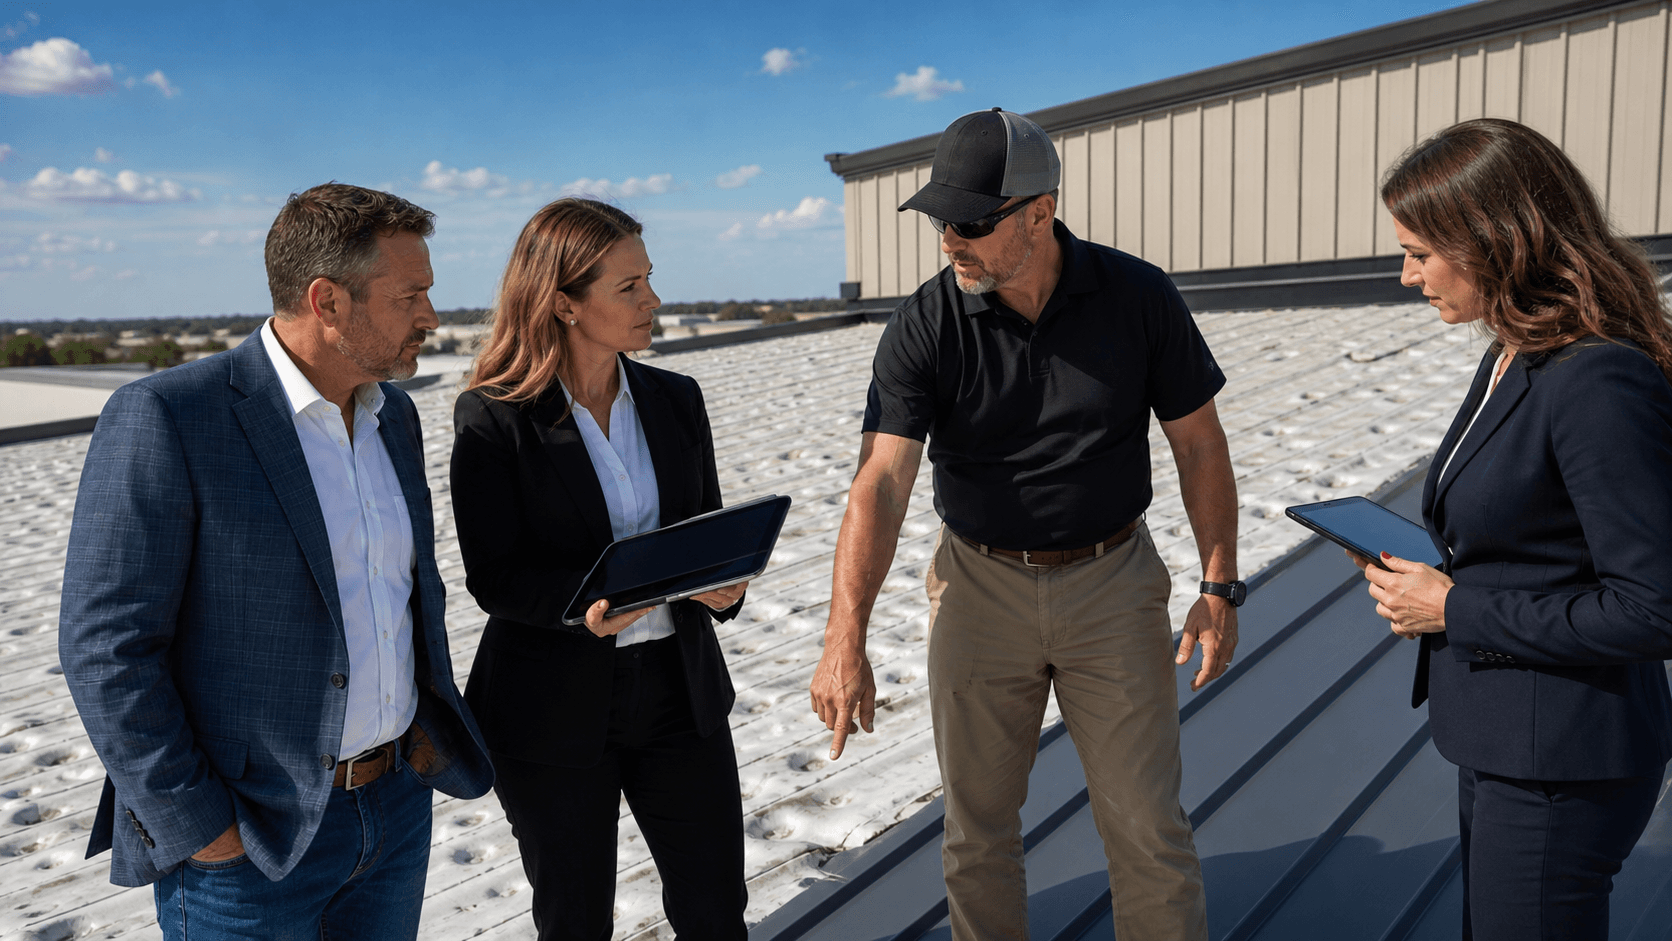
Hail is one of the most common property losses we see in Texas, especially for larger commercial roofs. Many owners assume that if hail hits the roof, the policy will take care of it. The surprise comes later when the commercial hail damage insurance claim turns into a fight over exclusions, sub-limits, or narrow readings of policy language.
Late summer and early fall can be a risky time. Spring hailstorms may have already weakened roofs, hurricane season keeps wind and hail in play, and many commercial policies are renewing. For portfolio owners, that mix can create quiet exposure on high-value assets.
In this article, we walk through coverage gaps and claim-handling problems we see over and over in Texas commercial hail losses. Our focus is on sophisticated policyholders, including REITs, developers, asset managers, institutional owners, and large private operators that depend on these properties for steady income.
Policy Language That Quietly Narrows Hail Coverage
The starting point is the policy itself. Many of the hardest problems in a commercial hail damage insurance claim grow out of endorsements that seemed harmless at binding.
Common trouble spots include:
- Sub-limits on roofs, exterior metal, or specific structures
- Cosmetic damage exclusions for visible dents or finish loss
- Roof-age or condition clauses that reduce what is paid
Sub-limits and cosmetic damage exclusions can gut recovery. A property can have a healthy overall limit, but a small sub-limit on roof damage. Cosmetic damage wording is another trap. Insurers often argue that dents in metal panels, impacts on façade systems, or finish damage to cladding are "cosmetic only," even when they affect:
- Long-term performance or watertightness
- Manufacturer or contractor warranties
- Market perception of a Class A or flagship asset
For large campuses, industrial parks, and retail centers with mixed roofing systems and elevations, each endorsement needs to be mapped against the actual construction.
Roof age and condition rules are another pressure point. Insurers may try to:
- Classify damage as "wear and tear" or "deterioration" rather than hail
- Reduce payment based on the age of the roof or material type
- Use small pre-existing issues as a reason to downplay fresh impact damage
Matching issues are common. A storm may strike certain slopes or elevations harder than others, but code, warranties, or basic building standards can require uniform materials and appearance. Insurers often push for patchwork repairs that do not align with:
- Current building codes
- Manufacturer installation instructions
- Tenant expectations and lease obligations
On top of that, some hail-specific endorsements go further and shift more risk onto the insured. We often see:
- Limits on certain roof types like modified bitumen, TPO, or metal
- Restrictions on how multiple hail events in the same policy term are treated
- Manuscript wording on large schedules or builder's risk placements that is not well understood at binding
These issues need to be flagged early in any serious loss, before key strategy decisions are made.
Deductibles and Valuation That Erode Recovery
Even when coverage is confirmed, structure and valuation can quietly eat into recovery.
Percentage wind and hail deductibles are a prime example. They are typically calculated on total insured value, so for a large location, the deductible itself can reach seven figures. On programs with multiple buildings or sites, the wording about "per building" or "per location" can drive major disagreements, including:
- Whether one storm equals one deductible or several
- How to treat campuses or mixed-use complexes written under one policy
- Whether multiple weather events during the term reset the deductible impact
Timing can also matter. A hail claim that surfaces late in the policy term may interact with earlier weather events and create arguments about what loss belongs to which date.
Valuation is another flashpoint. Many policies are written on a replacement cost basis but only pay actual cash value at first. The gap between the two can be large, and insurers often insist on strict conditions before paying replacement cost, such as:
- Completion of repairs within a certain time frame
- Disputes about whether the work was done "properly"
- Challenges to the scope and pricing used by the insured's consultants
These fights often center on expensive components like roofing systems, skylights, rooftop HVAC units, and high-finish interiors.
Ordinance or law coverage brings yet another layer. Modern codes and energy rules can require:
- Full tear-offs instead of overlays
- Upgraded insulation values
- Changes in attachment methods or edge details
Without enough ordinance or law limits, or with wording that ignores undamaged portions of the property, owners can be left carrying significant code-driven costs once the contractor is on site.
Causation and Scope Disputes in Hailstorm Claims
Many contested hail claims in Texas turn on cause and scope instead of outright coverage denials. Insurers often start by blaming problems on pre-existing conditions or poor maintenance. Defense themes we see again and again include:
- "This was ponding or long-term leakage, not hail"
- "This roof was at the end of its useful life before the storm"
- "Any hail marks are minor and do not matter"
Engineering reports are a common tool in that playbook. Some reports focus narrowly on only the most obvious fractures or punctures and ignore subtler but still important damage, such as:
- Loss of protective granules that shortens shingle or membrane life
- Bruising or mat fractures that are hard to see from the ground
- Coating damage on metal or single-ply systems that increases corrosion or UV exposure
There is also regular debate over what counts as "direct physical loss or damage." Insurers may classify widespread dents or marks on metal roofs, glazing, EIFS, or architectural finishes as cosmetic only. For Class A or signature properties, that position clashes with market expectations, lender standards, and long-term asset planning.
Initial scopes and pricing from adjusters or consultants often understate the real work required. Common omissions include:
- Underlayment, insulation, or tapered systems
- Flashings, curbs, and tie-ins to rooftop equipment
- Skylights, roof hatches, and other penetrations
- Code-required edge metal or safety features
Unit pricing and material substitutions that ignore manufacturer requirements or warranty terms are also common. For serious losses, owners are usually best served by building-by-building scopes developed by qualified experts, not just relying on the insurer's first estimate.
Business Interruption, Extra Expense, and Strategic Planning
For income-producing properties, the physical damage is only part of the exposure. Business interruption and extra expense can become the real pain point months after the storm.
Many policies carry limits that do not reflect actual income exposure. This can be a problem for:
- Hospitality and entertainment
- Retail centers dependent on foot traffic and parking
- Industrial or logistics sites that need uninterrupted access and utilities
Even if the building is not a total loss, hail-related repairs can close portions of the property, limit parking, or interfere with tenant operations. Construction delays or claim disputes can push out completion dates, long after the immediate cleanup is done.
The "period of restoration" and related policy wording then come into play. Insurers often argue that:
- Repairs could have been finished earlier, so BI should stop
- Delays caused by their own scope disputes or payment issues are not covered
- Work at one part of a multi-building site does not justify BI at others
When multiple locations or dependent properties are hit by the same storm, the analysis gets even more complex.
Proving time-element losses requires more than broad estimates. Owners typically need:
- Rent rolls and lease abstracts
- CAM reconciliations and historical income statements
- Tenant sales records where percentage rent is involved
- Construction schedules and change orders that show real-world delay drivers
Coordinated input from legal, accounting, and construction teams can protect these claims and reduce surprises late in the process.
Thoughtful pre-loss policy review and early post-loss strategy can shrink many of these gaps. For large Texas commercial portfolios, focusing on hail-specific sub-limits, deductibles, valuation terms, roof endorsements, and time-element coverage before the next storm can pay off when a significant commercial hail damage insurance claim lands on the table.
Protect Your Commercial Property Claim With Experienced Legal Help
If your business has suffered storm damage, we are ready to guide you through every step of your commercial hail damage insurance claim. At Lundquist Law Firm, we evaluate your policy, document your losses, and negotiate with the insurer so you can focus on running your operations. Reach out today so we can review your situation and outline a clear strategy for moving forward. To schedule a consultation, contact us.