Early Warning Signs Your Commercial Claim Is in Trouble
When a storm, fire, or pipe break hits a commercial property, the first weeks of the insurance claim can decide how the entire loss plays out. For Texas businesses and high‑value property owners, those early days are when the carrier starts building its coverage and valuation story, even if it feels like nothing much is happening yet.
If you miss the early red flags, you may lose leverage long before a denial letter or lowball payment shows up. That is especially true during busy hurricane and hail seasons, when adjusters are stretched and carriers lean on internal playbooks. As a Texas policyholder firm that used to sit on the carrier side, we have seen how quiet claim‑handling choices in the first 30 to 60 days can set up a delayed, denied, or underpaid outcome. The good news is that you can spot trouble early and respond in a way that protects your position.
Problematic Communications From the Adjuster
The first signs of trouble often show up in how the adjuster talks to you, and what they will not say.
Vague, shifting explanations for delays are a common pattern. Watch for:
- Repeated lines like "we are waiting on internal approvals" with no clear date or next step
- Statements that coverage is "still under review" even after you have answered all questions
- Multiple requests for the same documents you already sent, without any reason given
When a carrier has most of what it needs yet communication slows down or goes quiet, it can signal that it is developing a limitation‑of‑coverage position behind the scenes.
Another early warning sign is an immediate focus on exclusions instead of the event. If the first detailed letter spends pages on wear and tear, pre‑existing damage, construction defects, or faulty workmanship, but barely addresses the hail, wind, fire, hurricane, tornado, or internal water event, that is not a neutral "information update." Early reservation‑of‑rights letters that list every exclusion in the policy, without tying them to specific facts, often preview a denial strategy. At that point, getting guidance from an insurance claim denial lawyer in Texas can help you respond in writing and keep coverage arguments alive.
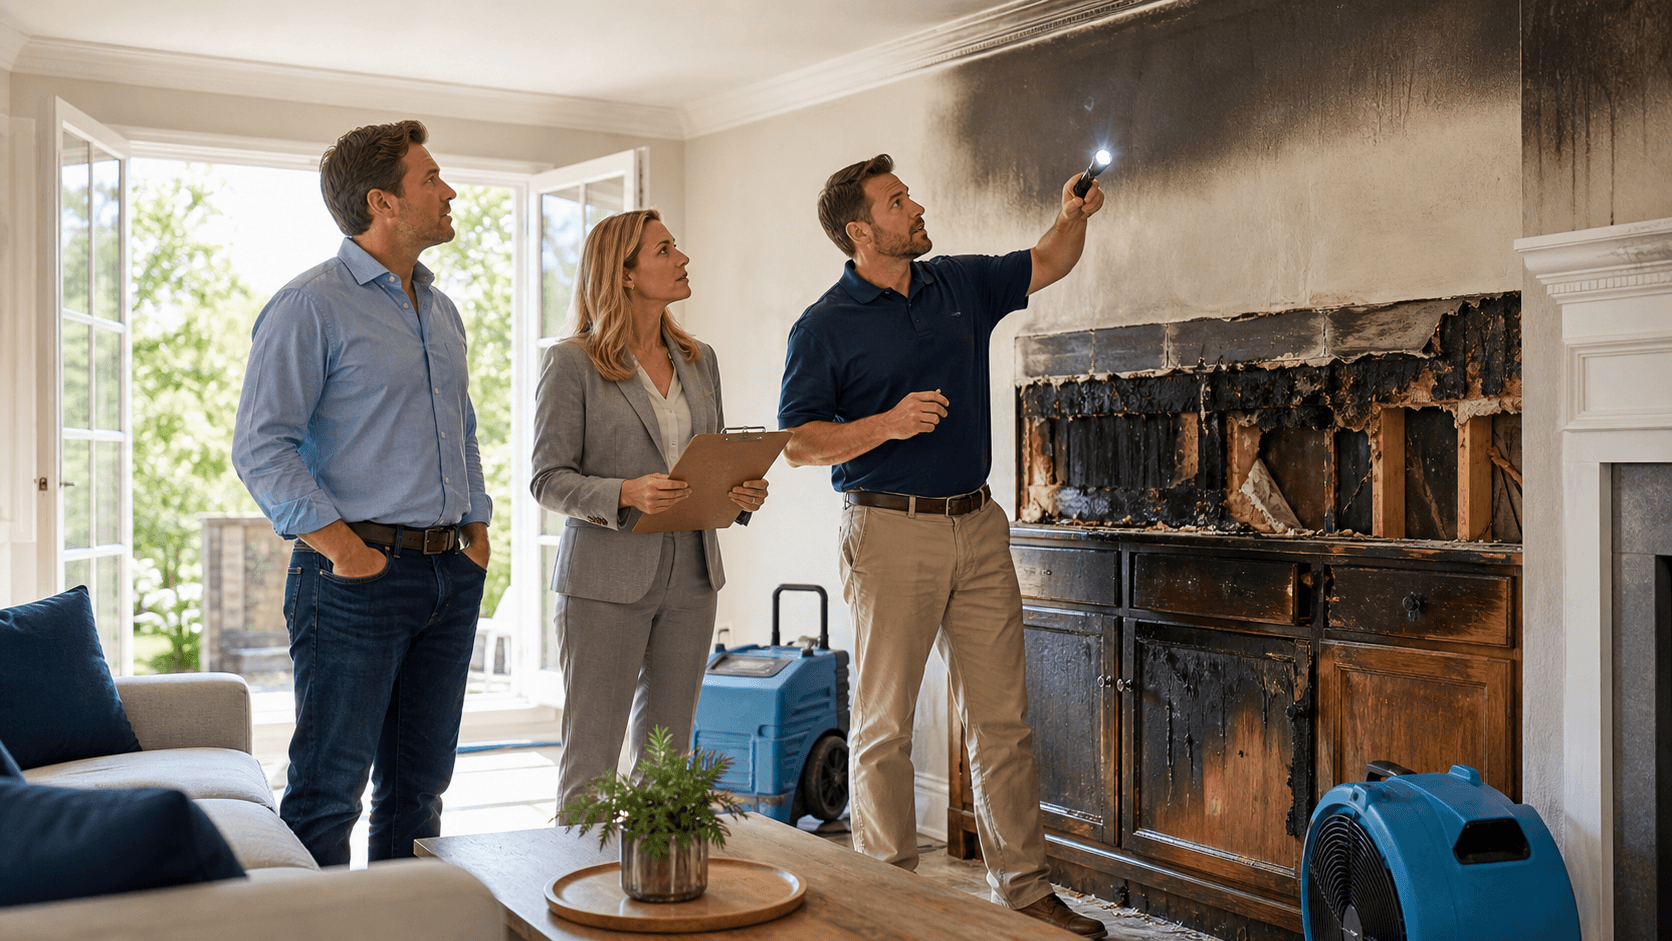
You should also pay attention to how site inspections are handled. Red flags include:
- Resistance to inspecting all damaged areas, including roofs, interiors, and mechanical spaces
- Rushed walk‑throughs for large or complex properties
- Attempts to limit who may attend inspections or speak, such as discouraging the owner, contractor, or restoration company
Sophisticated policyholders should insist on thorough inspections and keep their own record: notes, photos, and video. Allowing the carrier to control every detail of the inspection is an easy way for your loss story to be rewritten later.
Red Flags in the Investigation and Damage Scope
Once the adjuster starts framing the scope of damage, the carrier's strategy becomes clearer.
Superficial or one‑size‑fits‑all assessments are a major concern. Examples include:
- "Template" hail or wind scopes used across multiple buildings with different ages and materials
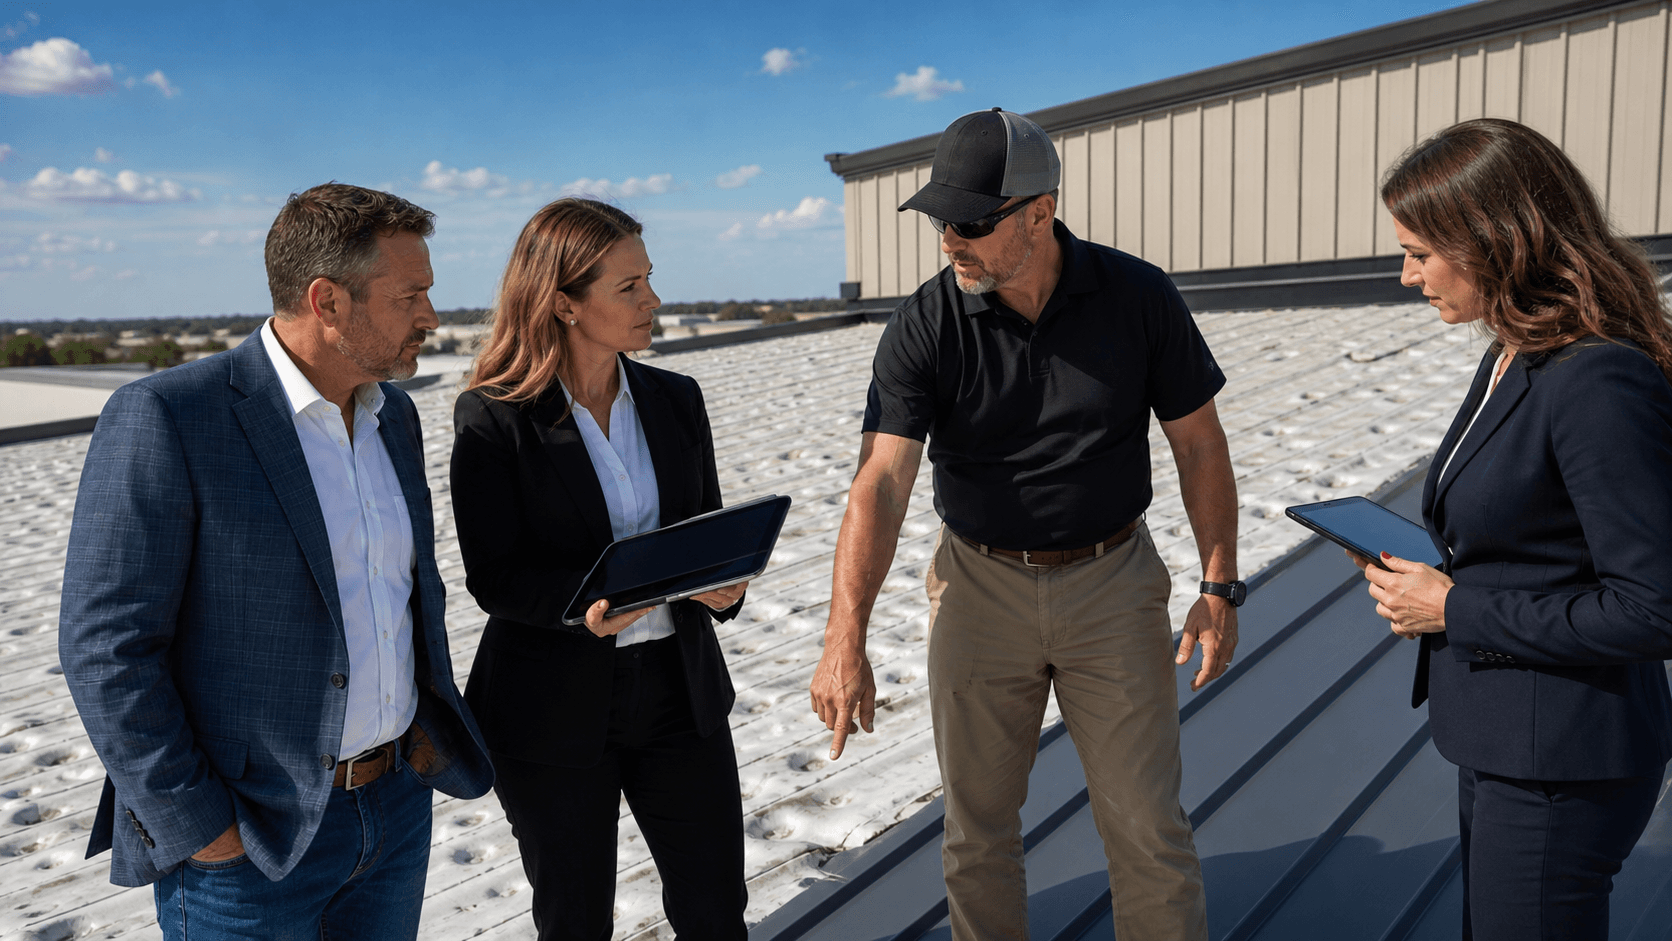
- Drive‑by or drone‑only reviews of serious roof or building‑envelope claims
- Scopes that ignore interiors, tenant build‑outs, specialty systems, or high‑end finishes
Large commercial properties, multi‑building campuses, and high‑value residential structures need detailed, line‑item scopes. When the carrier refuses to go that deep, it usually is not because it cannot, but because a shallow review is cheaper.
Ignoring or dismissing qualified experts is another warning sign. You may see:
- Carrier adjusters brushing off contractor, engineer, architect, or restoration reports that you provide
- "Desk reviews" where an internal consultant rejects your expert's findings without ever visiting the site
- No serious engagement of experts on major fire, internal water, or business interruption claims
Those steps often line up with an underpayment strategy: the less the carrier has to consider, the less it will pay.
Causation is a favorite battleground. Carriers may try to recast:
- Wind, hail, hurricane, or tornado damage as old wear and tear or lack of maintenance
- A sudden pipe break or plumbing leak as a long‑term seepage problem
- Damage from a specific event as pre‑existing or unrelated
Texas law on concurrent causation is detailed, and early disputes about "what really caused the damage" are a strong signal that you should speak with an insurance claim denial lawyer in Texas before you let the carrier's version harden into the official record.
Telltale Patterns in Early Valuation and Payment Behavior
Even when the carrier accepts that some damage is covered, you can still see clear signs that it plans to underpay.
Suspiciously low initial estimates are common. Be cautious when the first number:
- Leaves out code upgrades, permitting, and other soft costs
- Treats specialty build‑outs or luxury finishes like standard materials
- Blurs the line between replacement cost value and actual cash value
- Uses aggressive depreciation with little explanation
A very low estimate on an obvious major loss is rarely a good‑faith mistake. It often anchors the negotiation at a number that is far below what you actually need to repair or replace.
Carriers also use timing. Strategically timed partial payments may arrive:
- Right before quarter‑end, when the carrier wants to clear files off its books
- Just ahead of key business events, like tenant renewals or project deadlines
- After you push hard for answers, as a way to cool things down without solving the real dispute
These payments usually cover only the most obvious items like broken glass or emergency mitigation, while ignoring structural, electrical, mechanical, or interior build‑out losses. Accepting partial payments does not waive your rights, but you should clearly document in writing that you disagree with the scope and valuation.
For many businesses, the biggest financial hit is not the building damage; it is the lost income. That is why unexplained denials of business interruption coverage are such a concern. Watch for arguments that:
- Your suspension of operations was "voluntary"
- There was "no measurable loss," even when units were closed or occupancy dropped
- The period of restoration was shorter than what actually happened on the ground
Early, organized financial records like profit and loss statements, rent rolls, occupancy reports, and sales data are key to pushing back on those positions.
Documentation, Deadlines, and Policyholder Missteps Insurers Exploit
Insurers pay close attention to how you handle policy conditions. They know many businesses are busy, distracted, or unfamiliar with the fine print.
One tactic is overly aggressive use of sworn statements and Examinations Under Oath. Red flags include:
- Early demands for recorded statements before the carrier shares its own findings
- EUO requests in complex commercial fire, hurricane, tornado, or internal water claims when multiple entities are involved
- Tight timelines that do not give you time to gather documents or speak with counsel
EUOs are not casual conversations. Going in unprepared can create misstatements or gaps that the carrier later uses to attack your credibility or grounds for coverage.
Carriers also "weaponize" proof of loss and cooperation clauses. Watch for:
- Pressure to sign a proof of loss based only on the carrier's low estimate
- Short, inflexible deadlines for large volumes of detailed documentation
- Threats of denial for supposed "non‑cooperation" when you are in fact working to respond
The safest move is to track all deadlines in writing, request reasonable extensions when needed, and keep a clear record of your efforts to cooperate.
Silence can be as telling as pressure. Adjusters rarely highlight suit limitation provisions or other time‑sensitive conditions that cut off your rights. They also may say very little about coverage extensions such as:
- Ordinance or law coverage
- Extra expense coverage
- Code upgrade or increased cost of construction
- Debris removal
Business owners and property managers should get a full copy of the policy, with all endorsements, as early as possible in the claim. For complex or high‑dollar losses, reviewing that policy with experienced Texas policyholder counsel helps you understand what the carrier is not talking about, as much as what it is.
Turning Red Flags Into Strategic Leverage in Texas Claims
Red flags do not automatically mean you will lose your claim, but they do mean you should not continue on autopilot. When you see these patterns, it is time to tighten your approach: clean up your documentation, insist on written explanations, and think carefully before you agree to carrier‑driven narratives about scope, cause, or value.
A strong written record is your best tool. It helps you:
- Pin the carrier down on its reasons for delay or denial
- Show a clear pattern of cooperation on your side
- Preserve photos, videos, and expert reports that support your view of the loss
- Lay a foundation for extra‑contractual or bad‑faith remedies if the carrier's conduct crosses the line
At Lundquist Law Firm, we represent policyholders only, not insurers, in significant first‑party property disputes across Texas. Our work centers on complex commercial property losses, major residential fire and internal water claims, and serious business interruption disputes. When you start seeing early red flags like shifting explanations, lowball estimates, or aggressive proof‑of‑loss tactics, those are often the right inflection points to get experienced eyes on your file and evaluate your options before a denial or underpayment becomes final.
Protect Your Rights And Get Your Claim Back On Track
If your fire or property insurance claim has been denied or underpaid, we are ready to review your situation and explain your legal options. As an experienced insurance claim denial lawyer in Texas, Lundquist Law Firm can help you challenge the insurance company's decision and pursue the coverage you paid for. Reach out today to tell us what happened and let us assess your claim. If you are ready to take the next step, contact us to schedule a consultation.