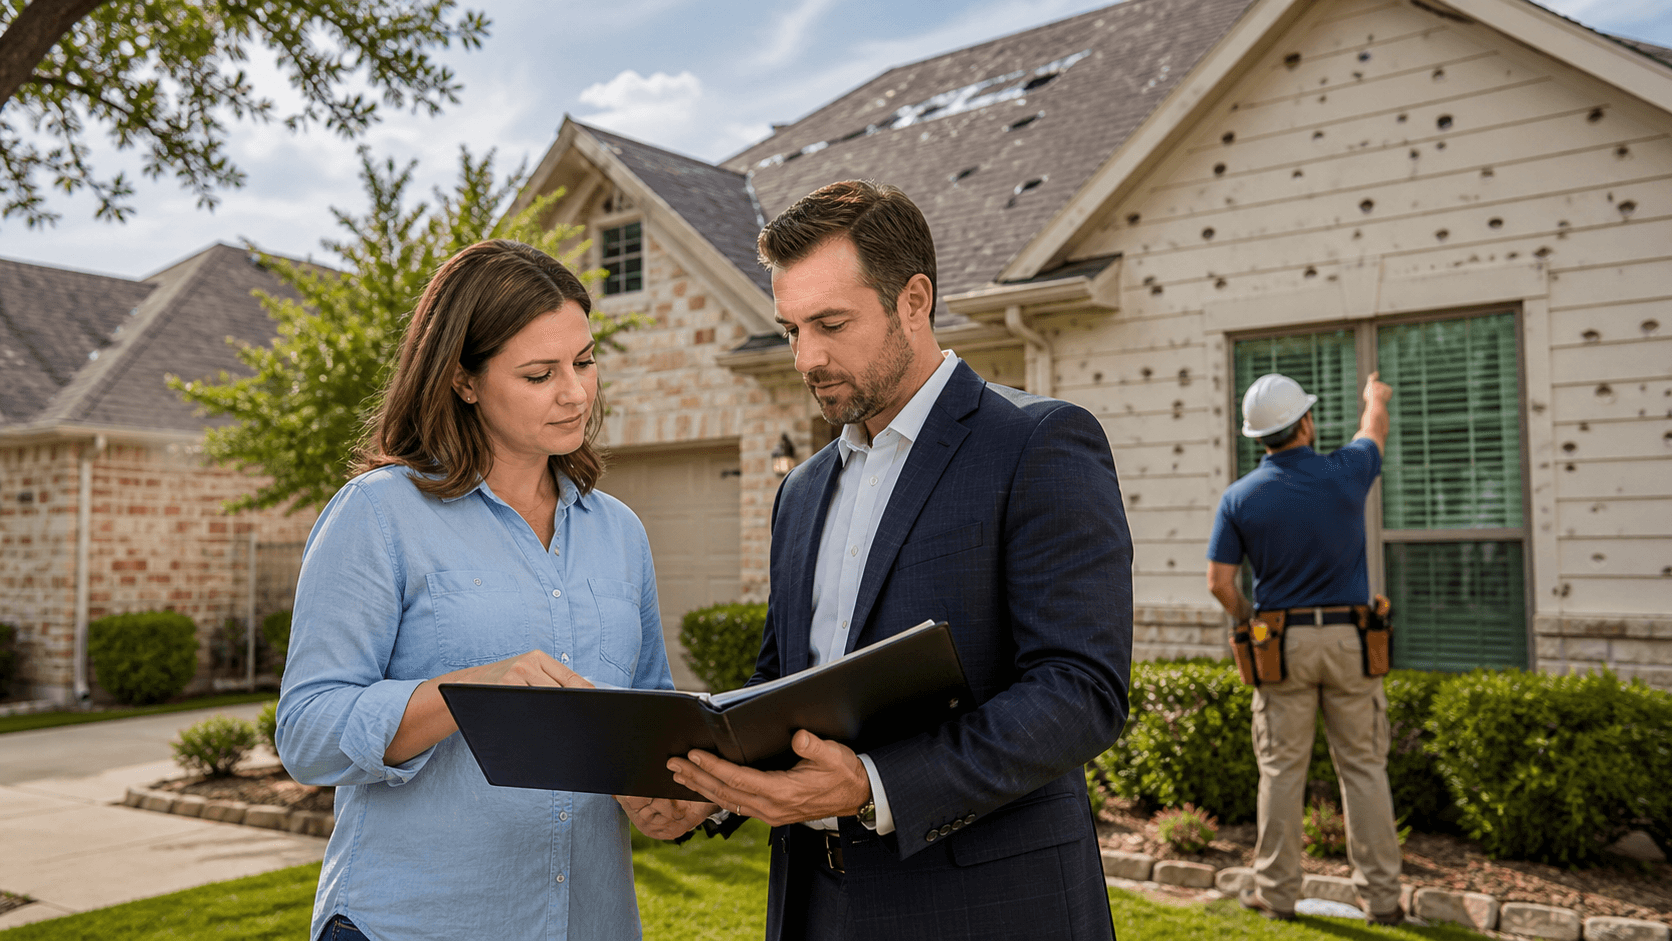
When an insurer tells you that you missed a deadline, it can feel like the whole claim just fell off a cliff. For many Texas commercial policyholders, that message shows up for the first time in a denial letter or a reservation of rights, long after you thought the claim was moving forward. The timing issue often surfaces right when you are already drained from dealing with property damage, business interruption, and internal pressure from stakeholders.
In late summer and into the storm-heavy months, these problems spike. Adjusters are stretched thin, property owners are juggling emergency repairs and tenant demands, and email threads get long and messy. In that chaos, notice dates, proof-of-loss deadlines, and suit limitation periods can slip. The real question is simple: if a deadline was missed, is your Texas property damage claim over, or do you still have real options to protect your recovery?
When a Missed Deadline Threatens Your Insurance Recovery
In commercial claims, the first time anyone on your team hears the words late notice or expired limitation is often after months of back and forth with the carrier. You may have already allowed inspections, shared financials, and answered long question sets, only to be told the claim is barred on timing grounds.
This happens most often around:
- Hurricane and windstorm season
- Large hail events across Texas
- Tornado or severe thunderstorm outbreaks
- Major internal water losses like pipe bursts or sprinkler failures
During those periods, it is easy for a policy condition or obscure endorsement to get overlooked. Insurers know this. Timing becomes a convenient pressure point in high-value property and business interruption disputes, especially when the loss involves multiple buildings, complex leases, or layered ownership structures.
Our work focuses on those kinds of first-party property and business interruption disputes for policyholders only, and we see timing used as a weapon on a regular basis. The good news is that a timing issue often signals the start of a legal analysis, not the automatic end of the claim.
The Deadlines That Can Make or Break Your Claim
Most commercial property policies that respond to hail, wind, tornado, hurricane, fire, and smoke, and internal water losses are packed with time-sensitive requirements. The main categories include:
- Notice of loss requirements, like prompt notice or as soon as practicable
- Sworn proof-of-loss deadlines, such as within a set number of days after request
- Contractual suit limitation provisions that shorten the time to file suit
- In some situations, pre-suit notice requirements under Texas statutes
These requirements are not always obvious. They may be tucked into:
- Endorsements that apply only to certain locations or causes of loss
- Business interruption or extra expense forms
- Separate conditions for named storm or windstorm coverage
Insurers often treat phrases like prompt notice or within X days as if they are crystal clear. In real life, they are not. Damage can be latent. Roof or envelope issues might only become clear after the next major rain. The full scope of business interruption can take time to develop as tenant issues and repair delays stack up.
On top of that, Texas law also imposes certain timing duties on the insurer itself, for acknowledging, investigating, and paying claims. When a carrier accuses an insured of delay while taking its own time on coverage decisions, that contrast can become part of the policyholder's leverage.
Insurer Tactics When They Claim You Were Too Late
After a major loss, timing arguments are often part of a broader defense strategy. Carriers may:
- Assert late notice or late proof of loss as a basis to deny or limit coverage
- Argue that emergency repairs destroyed key evidence, calling it spoliation
- Use the passage of time to question whether hail, wind, or internal water actually caused the claimed damage
You may see themes like:
- Claims that the carrier was prejudiced, meaning it was supposedly harmed by the delay
- Heavy reliance on engineers who blame wear and tear or maintenance issues
- Aggressive accounting positions in business interruption, tied to a narrow view of the covered period of restoration
For large commercial or high-value residential losses, these timing complaints often appear alongside low valuations, narrow scopes, and critical expert reports. In reality, the carrier may have adjusted the claim for months without treating it as forfeited.
A Texas property damage claim lawyer will usually start by testing the story the insurer is telling about delay. Can the carrier show real prejudice, given the inspections, documents, and access it already had? Did it keep adjusting the claim, issue partial payments, or request more information after the supposed deadline passed?
Legal Tools for Salvaging a Late or Disputed Claim
Even if a deadline has technically passed, there are legal concepts that can keep a claim alive. The key ideas often include:
- Waiver, where the carrier's words or conduct give up its right to enforce a deadline
- Estoppel, where the insured reasonably relies on the carrier's actions or assurances
- Texas notice-prejudice principles in appropriate coverage contexts
Evidence of waiver or estoppel can show up in everyday claim activity, such as:
- Ongoing email chains about scope, pricing, or business interruption calculations
- Multiple inspections long after the alleged deadline
- Partial payments or advances issued without reserving rights on timing
- Written extensions or informal agreements to keep adjusting the claim
Business interruption claims in particular usually cannot be wrapped up quickly. The period of restoration, replacement timelines, supplier issues, and tenant churn all affect the numbers. When a carrier spends months trading spreadsheets and backup, it can be difficult for it to later claim that an early deadline absolutely bars the claim.
For major hail, windstorm, tornado, hurricane, fire, or internal water losses, a careful review of:
- Emails and letters between your team and the adjuster
- Internal reports from the insurer's field and desk adjusters
- Reservation of rights letters and coverage position letters
can uncover strong arguments that the insurer waived the deadline or cannot show any real prejudice from the timing of notice or proof.
These doctrines are fact-heavy and very context specific. The details that matter legally are often not obvious to non-lawyers.
Strategic Steps If You Suspect a Deadline Problem
If you think a deadline might be an issue, try to slow down your reaction and get organized. A practical response plan usually includes:
- Preserving all claim-related emails, letters, photos, and videos
- Keeping contractor, engineer, and consultant reports together in one place
- Saving repair invoices, change orders, and business interruption documentation
- Avoiding casual emails that admit fault or accept the carrier's timing position
Internal risk managers, brokers, and public adjusters play important roles. But contractual limitation periods, Texas Insurance Code issues, and bad faith theories are legal problems. They sit in a different bucket from routine claim handling.
One helpful exercise is a focused claim audit:
- Pull the policy and highlight all notice and suit-limitation language
- Build a real timeline, including first awareness of damage and first carrier contact
- Note temporary repairs, mitigation steps, and when full damage was discovered
- Track the carrier's delays, extension requests, and periods of inactivity
With that groundwork, a Texas property damage claim lawyer can help recalibrate the discussion. That might include correcting the record on timing, developing waiver and estoppel arguments, evaluating whether new or supplemental claims are appropriate, and preparing for litigation if that becomes necessary.
Sophisticated commercial owners and residential policyholders facing serious fire or internal water losses should think of deadline disputes as legal issues, not paperwork mistakes.
Turning a Timing Dispute Into a Strategic Advantage
A missed or disputed deadline often marks a turning point. It is usually not the final word on your recovery, especially on substantial commercial claims involving office buildings, retail centers, industrial facilities, multifamily properties, or hospitality assets. The same is true for high-value residential claims where fire or internal water has disrupted normal life.
For high-exposure files like these, the dollars at stake are too significant to walk away based on a single timing argument without a deeper review. A focused legal analysis of policy language, claim history, and insurer conduct can show whether the carrier's timing defense is truly enforceable, open to negotiation, or vulnerable in court.
At Lundquist Law Firm, we represent policyholders only in first-party property and business interruption disputes across Texas, including complex, high-value matters where carriers lean heavily on technical defenses like alleged late notice or expired suit limitations. When timing becomes the story, a careful look at the facts and the law can change the ending.
Protect Your Property Rights With Experienced Legal Help
If your insurer is delaying, underpaying, or denying your claim, we are ready to help you take the next step. As an experienced Texas property damage claim lawyer, Lundquist Law Firm can evaluate your situation and outline your best legal options. Reach out today so we can review your documents, explain what to expect, and start building a strategy tailored to your loss. If you are ready to talk about your case, contact us to schedule a consultation.