Reservation-of-Rights Letters in Texas Property Claim Denials
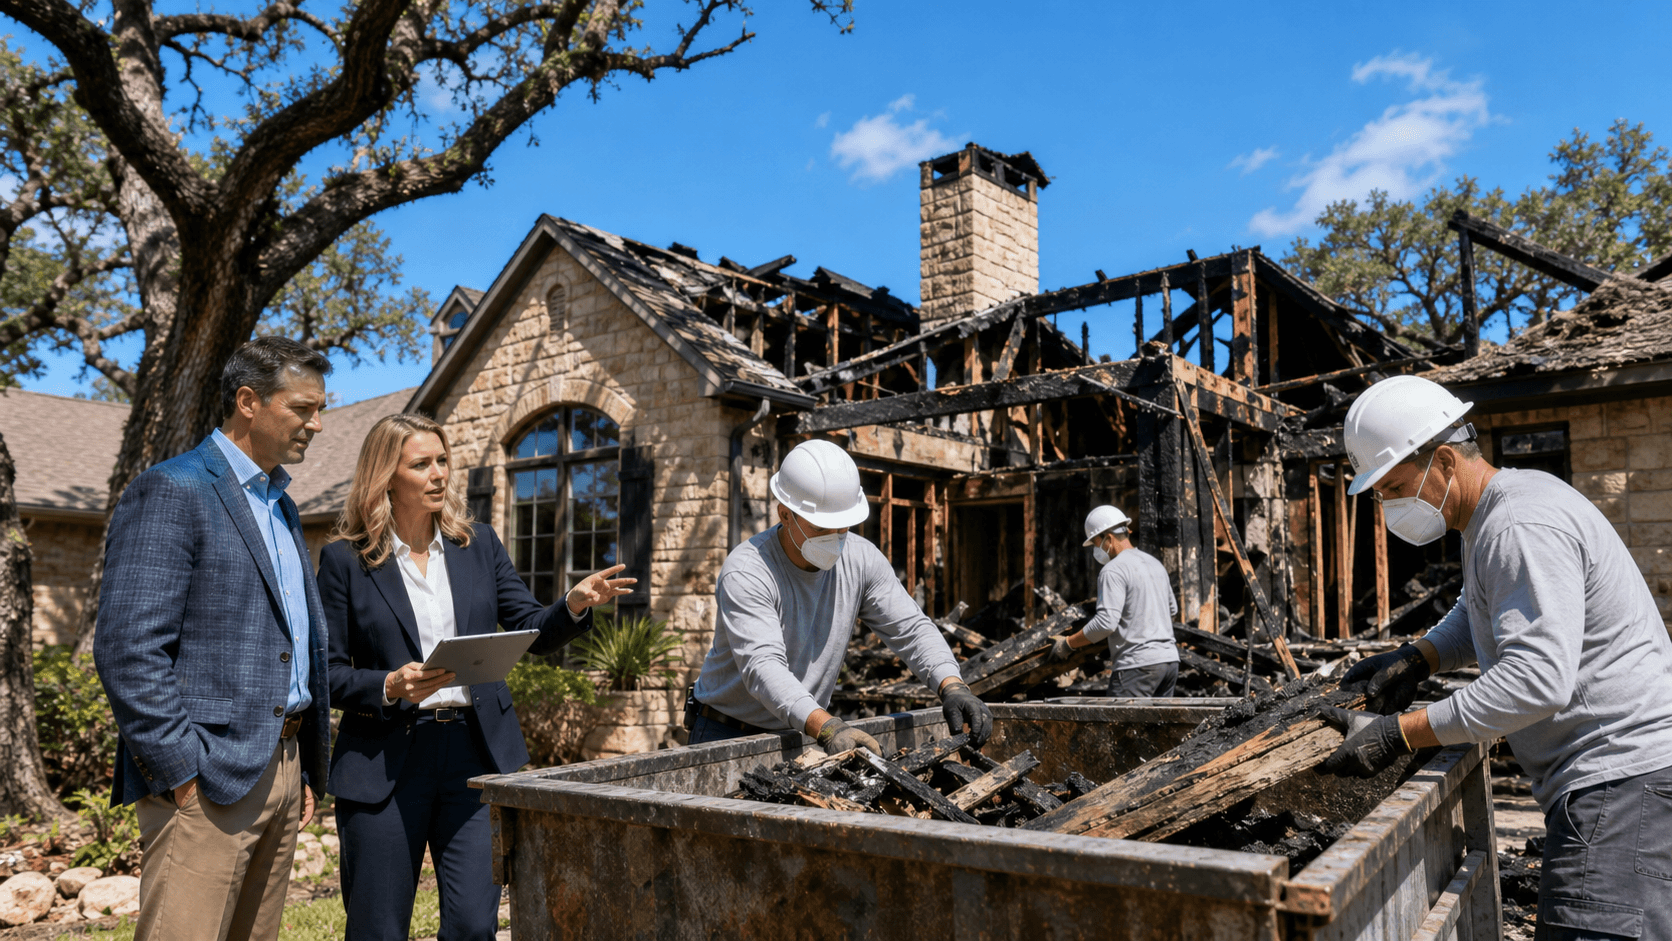
Reservation-of-rights letters are not always final denials, but they should never be treated as routine paperwork. For Texas property owners and business decision-makers dealing with a major fire, hail, windstorm, pipe burst, sprinkler failure, or lost-income claim, the letter may reveal how the insurer intends to limit coverage.
We view these letters as an early signal to examine the claim closely. The practical question is whether the carrier is conducting a fair, fact-based investigation or building a record to delay, reduce, or deny payment under the policy.
What a Reservation-of-Rights Letter Does
Such a letter generally tells you that the insurer will continue investigating or adjusting the loss while preserving one or more potential coverage defenses. The carrier may cite exclusions, policy conditions, definitions, deductibles, or endorsements it believes could affect payment.
To be meaningful, the letter should identify the policy language at issue and explain the facts the insurer believes may matter. It should not simply list every exclusion in the policy without connecting those provisions to the actual loss. Broad, vague language may be a sign that the insurer has not reached a supported coverage position.
Importantly, a reservation of rights does not give the insurer new exclusions that do not appear in the policy. It also does not excuse poor claim handling, unreasonable delay, or an incomplete investigation. We often recommend early review because the insurer's description of the facts is not the final word on what happened or what the policy covers.
Review by an insurance claim denial lawyer in Texas can assess the letter alongside the full policy and the available loss evidence. That review may identify unsupported assumptions, overlooked coverage extensions, or conditions the insurer has raised without a clear factual basis.
Policy Terms Insurers Often Raise After a Property Loss
Coverage disputes often begin with a short list of familiar provisions. Yet whether a provision actually applies can depend on engineering findings, repair records, weather evidence, contractor observations, accounting documents, and the policy's exact wording.
Insurers may point to:
- Wear and tear, deterioration, or deferred maintenance exclusions
- Repeated leakage or alleged long-term plumbing conditions
- Vacancy provisions or protective safeguards requirements
- Duties after loss, including document requests and examinations
- Claims that the insured failed to meet a policy condition
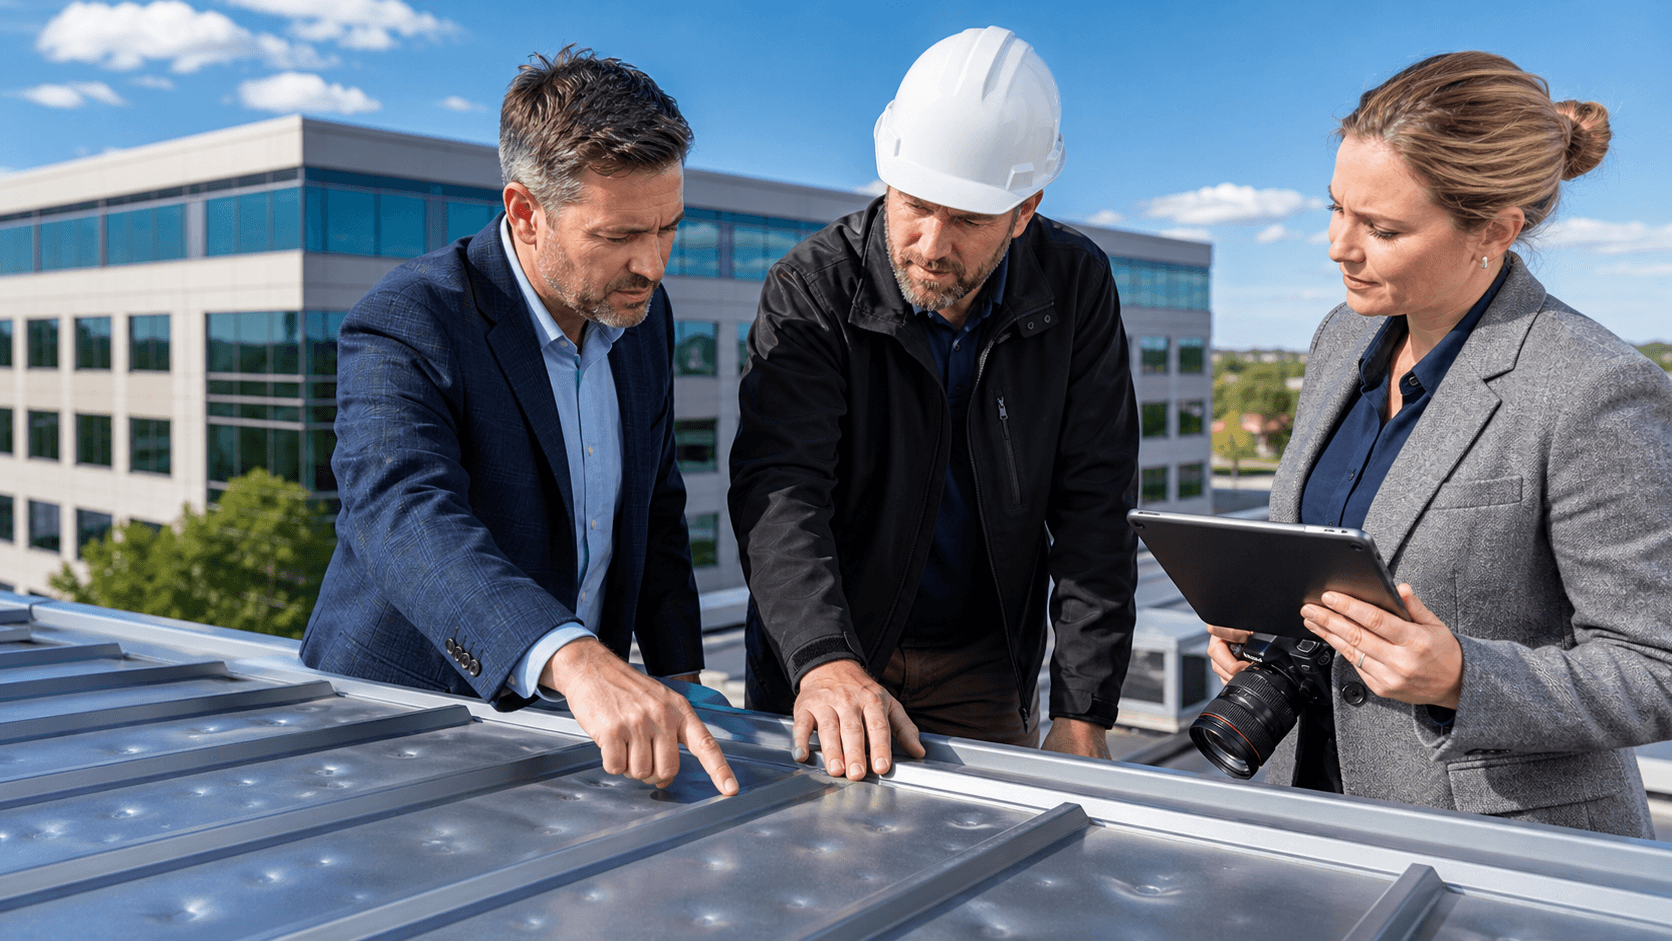
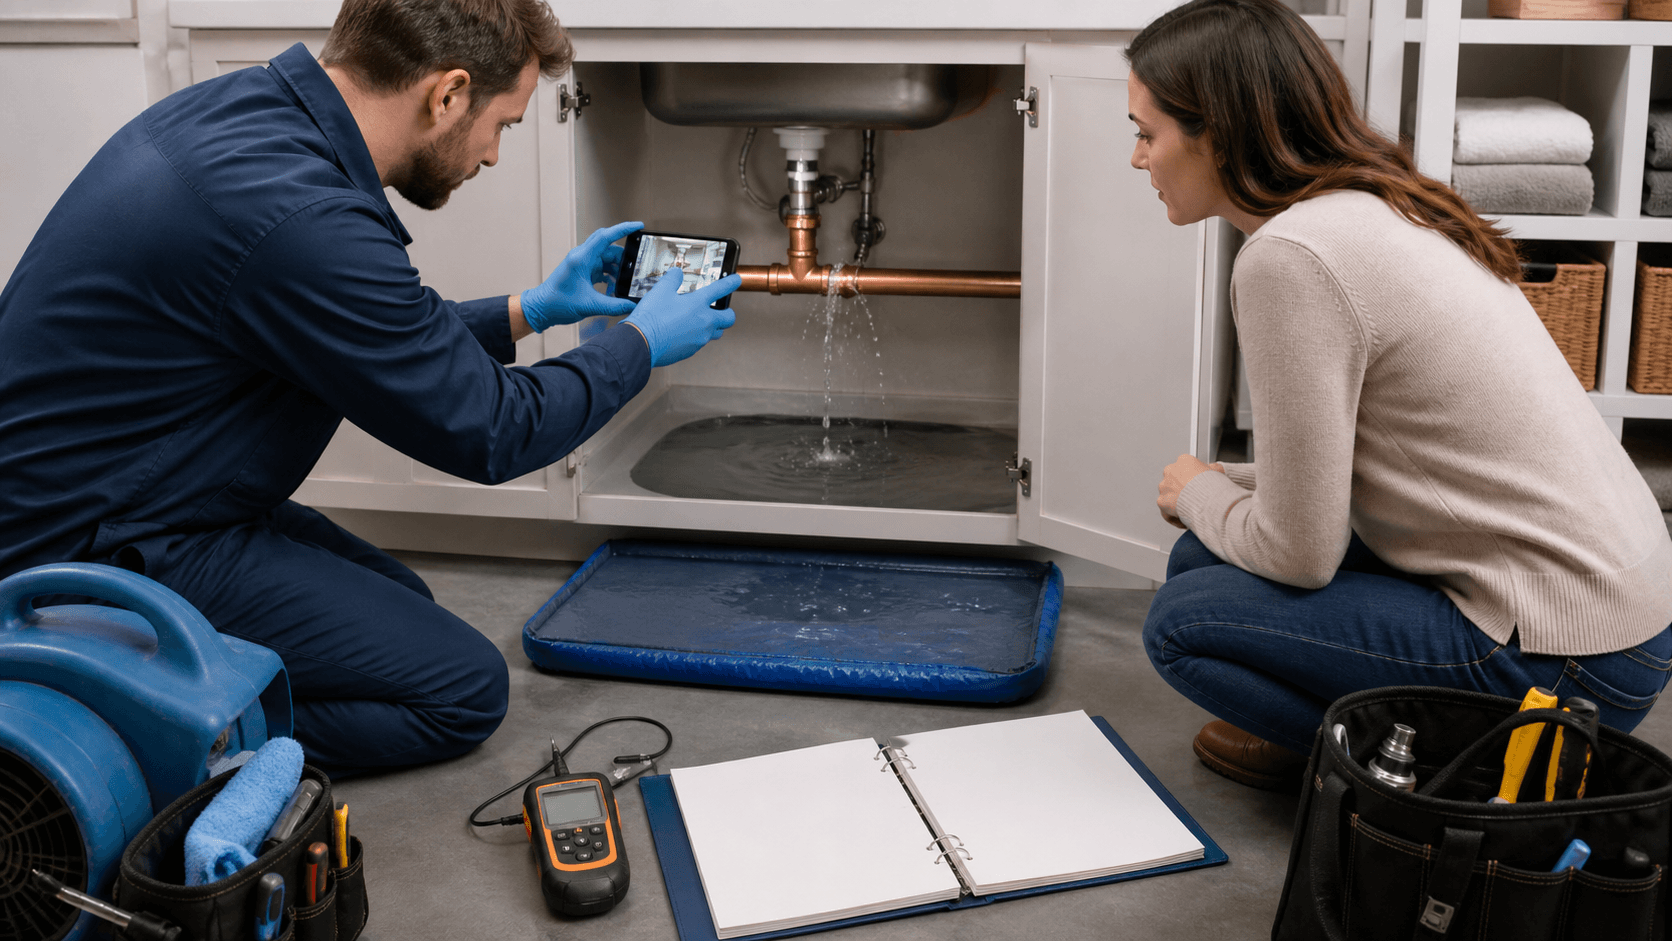
For example, an insurer may characterize a sudden pipe burst or sprinkler failure as a maintenance problem that developed over time. After a hail or wind event, it may argue that roof or exterior damage existed before the storm. Those positions can affect more than the physical repair scope. They may also affect business interruption, extra expense, and lost-income portions of a commercial claim.
The complete policy matters. Endorsements can change standard terms, add coverage, alter deductibles, or provide separate limits. We look beyond the insurer's initial summary to evaluate coverage extensions that may apply to debris removal, code-related work, extra expense, or loss of business income. A sophisticated commercial claim should not be evaluated from selected policy pages alone.
Signs a Denial May Be Developing
Some reservation-of-rights letters are narrow and tied to a real issue. Others indicate that the insurer may be developing a broader coverage defense. The concern is not simply that the carrier asked questions. A legitimate investigation may require records and access to the property. The concern is whether the requests and stated defenses match the loss.
Warning signs can include:
- Repeated references to an "ongoing investigation" with no clear timeline
- Multiple unrelated exclusions listed without supporting facts
- Demands for expansive historical records after the property has been inspected
- Continued claims that information is missing after you have provided documents
- Delayed expert opinions, shifting damage scopes, or changing causation theories
We also see insurers separate building damage from business interruption without a sound factual reason. A carrier may accept limited repairs while questioning whether the loss disrupted operations, whether the restoration period was reasonable, or whether claimed income loss is tied to the covered event.
Preserving evidence early can make a significant difference. Keep damaged materials when appropriate, photographs, contractor reports, inspection records, repair estimates, invoices, communications with adjusters, and records showing the operational impact of the loss. Before giving broad recorded statements, authorizations, or responses, many insureds benefit from understanding what the policy requires and what the insurer is actually seeking.
A Precise Response Can Protect Your Coverage Position
Well-supported responses do more than disagree with the insurer. They address the carrier's stated concerns directly, correct inaccurate factual assumptions, identify relevant policy language, and provide evidence that supports the claimed loss. They may also request that the insurer state its coverage position clearly rather than leaving the claim in an open-ended investigative status.
Cooperation with a reasonable claim investigation does not require you to accept an unsupported coverage theory. Commercial insureds can provide relevant documents while preserving objections to demands that are overbroad, duplicative, or disconnected from the claimed loss. The same applies when an insurer adopts a narrow repair scope or relies on a causation opinion that does not account for all available evidence.
When delay, underpayment, or denial continues, an insurance claim denial lawyer in Texas can evaluate the contractual issues and potential concerns involving unfair or unreasonable claim handling. In a complex property loss, we may also work with qualified contractors, engineers, accountants, and other technical professionals whose findings can clarify the cause of loss, repair scope, and business-income impact.
Put the Insurer's Position Under Careful Review
Texas storm, wind, hail, and fire losses can create fast-moving claim disputes, especially when a commercial property has significant repair needs or operations are interrupted. A reservation-of-rights letter should prompt careful organization, not panic. Gather the complete policy, endorsements, insurer correspondence, estimates, photographs, expert reports, repair records, and claim communications in one place.
Careful review of the reservation-of-rights letter, the complete policy language, and available loss evidence can help determine whether the carrier's position is grounded in the contract or primarily aimed at limiting payment.
Develop a Focused Response to the Denial
Lundquist Law Firm represents policyholders facing disputed property insurance claims, including commercial losses and residential fire claims. An insurance claim denial lawyer in Texas can assess the carrier's stated grounds, preserve critical evidence, and develop a strategy tailored to the policy and loss. To discuss your claim with our team, contact us for a confidential consultation.